Showing posts with label Goods and Services Tax. Show all posts

Wednesday, May 30, 2018

Change of GST rate from 6% to 0%


On 16 May 2018, the Ministry of Finance has announced that the change of the Goods & Services Tax (GST) rate from 6% to 0% effective from 1 June 2018. However, all GST registrant are still subjected to all current regulations, such as:
  1. Issue of tax invoice
  2. Submission of GST-03 returns
  3. Input tax claims

The Malaysian Customs Department (RMCD) has issued and uploaded the GST-FAQ on transitional from 6% to 0% on their website.

The Sales and Services Tax (SST) will be implemented from 1 September 2018 to replace the Goods and Services Tax (GST).


Tuesday, February 06, 2018

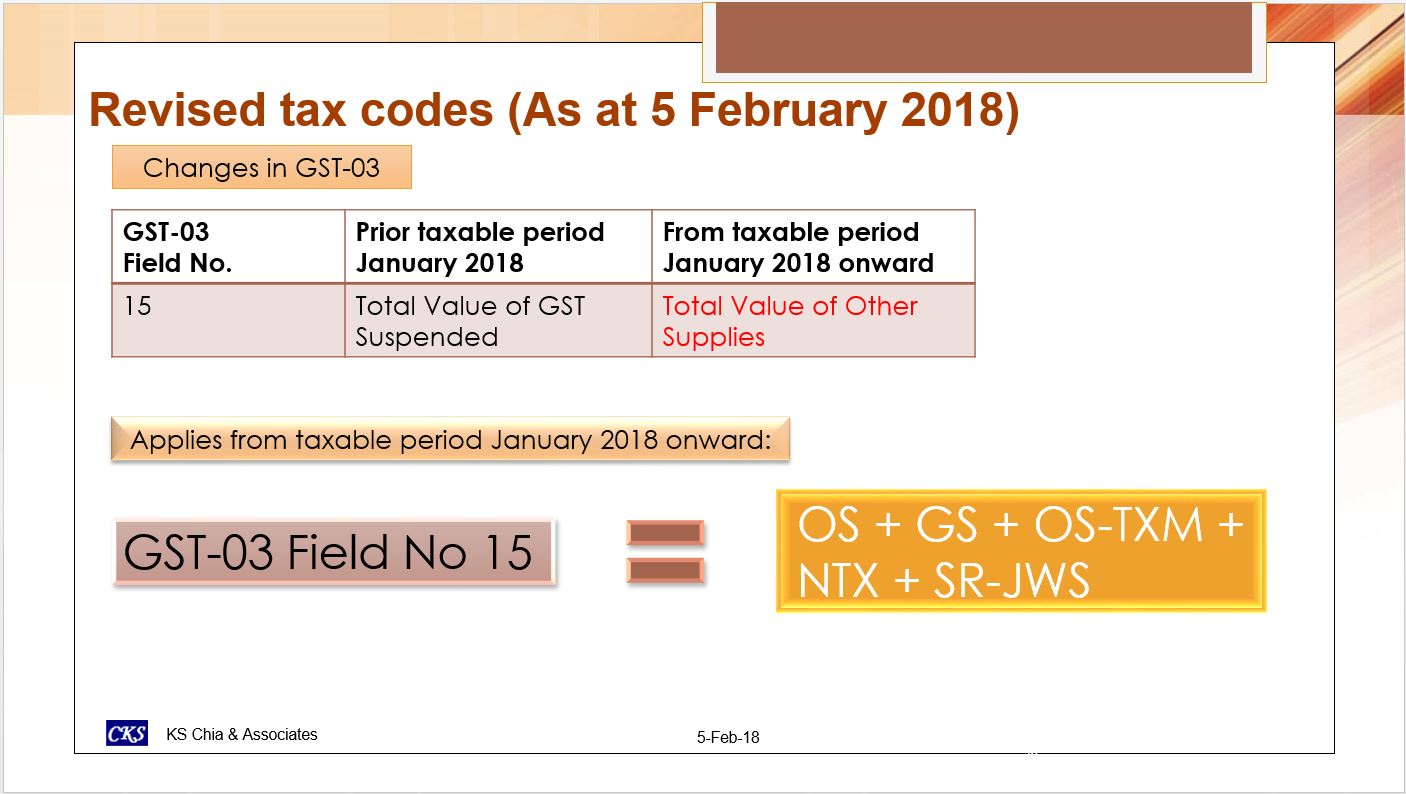
Revised tax codes (As at 5 February 2018)

RMCD officially uploaded the revised of “The Guide of Accounting Software Enhancement towards GST Compliance” as at 5 February 2018. The new guide replaced the Guide dated 2 March 2017.

The new guide withdraws the tax code NP and reinstate tax code IM-CG.

From the taxable period January 2018 onwards, item 15 of GST-03 return has been amended from "Total Value of GST Suspended under Item 14" to "Total Value of Other Supplies".

The total value of other supplies includes out of scrap supplies and disregarded supplies.


Monday, March 06, 2017

Revised GST Tax Code as at 2 March 2017

The Royal Malaysian Customs Department (RMCD) has issued the revised Guide on Accounting Software Enhancement towards GST Compliance as at 2 March 2017. This revised Guide replaces the previous Guide as at 1 August 2016.

http://gst.customs.gov.my/en/rg/SiteAssets/accounting_software/GUIDE_ON_ACCOUNTING_SOFTWARE_02MAC2017.pdf


RMCD has uploaded new revised the “GUIDE ON ACCOUNTING SOFTWARE ENHANCEMENT TOWARDS GST COMPLIANCE” as at 5 February 2018 to replace the previous guide.

The following tax codes have been combined as ZP:-


a) EP: Purchase in relation to exempt supply under GST legislation
b) RP: Relief Purchase under GST legislation
c) GP: Purchase transactions which disregarded under GST legislation.

The new guide withdraws the tax code NP and reinstate tax code IM-CG.

From the taxable period January 2018 onwards, item 15 of GST-03 return has been amended from "Total Value of GST Suspended under Item 14" to "Total Value of Other Supplies".

The total value of other supplies includes out of scrap supplies and disregarded supplies.

Wednesday, November 23, 2016

SUGGESTED TAX CODE FOR MOTOR VEHICLE


Type of accounts
Commercial
Passenger
Balance sheet


Motor vehicles 
TX
BL


Income statement


Battery – Hybrid car
-
TX*
Hire of motor vehicle
TX
BL
Insurance
TX
TX*
Inspection fee
TX
TX**
Parking
TX
TX*
Petrol – RON 97
TX
TX*
Repair, maintenance and refurbishment
TX
BL


Source:
* Technical Committee For GST Implementation (TC-GST Imp) Minutes of Meeting No. 5/2015
** Confirmed during "Half-Day Talk: Updates On GST" on 14 November 2016

Wednesday, July 20, 2016

NEW TAX CODE

On 29 August 2016, RMCD has announced Guide "Accounting Software Enhancement Towards GST Compliance (Revised as at 1 August 2016)" has been removed from their website.

http://gst.customs.gov.my/en/ib/SiteAssets/Notice/ANNOUNCEMENT_REMOVAL_GUIDE_ACCOUNTING.pdf


The Royal Malaysian Customs Department (RMCD) has uploaded the revised Guide onAccounting Software Enhancement towards GST Compliance. 

Here is the summary of the new tax code.

New Tax code for Purchase
Tax code
Description
Example
TX-CG
Purchase with GST incurred for capital goods acquisition.
Purchase of fixed assets with GST (claimable) (i.e. office equipment, machinery, commercial vehicle, factory building…)
RP
Relief Purchase under GST legislations.
Purchase of RON95, Diesel and other relief supply

New Tax code for Purchase (Mixed supplier)
Tax code
Description
Example
TX-FRS
Purchase under Flat Rate Scheme.
Purchase from a person who qualifies for Flat Rate Schemes
TX-NC
GST incurred but chooses not to claim the input tax.
Tax invoice incomplete information
TX-ER


Input tax allowed on the acquisition of goods or services by local authority or statutory body.
Expenses incurred on SSM e-info
IM-CG
Import of goods with GST incurred for a capital goods acquisition.
Purchase of fixed assets from oversea.
IM-RE
Import of goods with GST incurred that is not directly attributable to taxable or exempt supplies (Residual input tax).
-

(Note : Tax code TX-ER, IM-CG & IM-RE have been removed from Guide on 2 March 2017) 


Tuesday, July 28, 2015

GST DG'S DECISION 7/2015

DG'S DECISION 7/2015 dated 27 July 2015 uploaded by Customs. 

Utilities bills registered under landlord name now allow to claim input tax but subject to certain conditions & valid until 31 March 2016...

1) The property owner is not a GST registered person;
2) There must be a tenancy agreement signed by the property owner and the tenant; 
3) There must be a clause in the tenancy agreement or a written declaration signed by both the tenant and property owner in a separate document stating that “the input tax on the electricity and water invoices/bills can only be claimed by the tenant. However if the property owner becomes GST registered person, the tenant is not allowed to claim the input tax using such invoices/bills.”
4) The tenant must keep records of the input tax claimed for the electricity and water invoices/bills under the name of the landlord; and
5) The tenant shall stop claiming ITC using electricity and water invoices/bills under the name of the property owner once the property owner becomes a GST registered person. In this case the normal GST rules apply where the landlord will have to issue a tax invoice and charge GST to the
tenant. The tenant can use the tax invoice for claiming the ITC

Wednesday, May 06, 2015

GST DG Decision No. 5/2015

On 30 April 2015, the Royal Malaysian Customs Department (RMCD) has issued the decision DG's Decision 5/2015. The GST issues related to the following:-

1. Document for claiming special refund.
2. Claiming Special Refund in respect of imported CBU car held on hand 31 March 2015.
3. Special Refund on stock of raw materials or components held on hand on 31 March 2015.
4. Cost recovery under warranty.
5. A gift of goods worth more than RM500.
The Director General has confirmed a registered person whether claims or not to claim the input tax credit on the goods, the registered person still has to account for output tax if the gift of goods is worth more than RM500.
6. Disbursement and Reimbursement.
The DG has explained the GST treatment and the criteria for disbursement and reimbursement.

7. Transport services.

Sources : RMCD website

Wednesday, April 22, 2015

GST DG Decision No. 3/2015


The Royal Malaysian Customs Department (RMCD) has issued the decision on GST Director General's (DG) Decision 3/2015. The GST issues related to the following:-
 
1.   Application for Self Billed Invoice.
Stated the procedures for apply Self Billed Invoice.

2.   Issuance of tax invoice at the beginning of GST implementation.
The following business must use a GST compliant point of sale (POS) system or a GST compliant cash register to issue GST tax invoices beginning 1st October 2015:-
(a) Hardware shop
(b) Restaurant including coffee shop
(c) Mini market, grocery and sundry shop
(d) Book store
(e) Pharmacy
(f) Places of entertainment
The Directors General has confirmed that GST registered person is not allowed to issue any handwritten tax invoices

Thursday, March 26, 2015

GST DG Decision No. 2/2015

The Royal Malaysian Customs Department (RMCD) has issued the decision on GST Director General's (DG) Decision 2/2015. The GST issues related to the following:-

1. Small Office Home Office (SOHO)
2. Supply of commercial property by the developer to purchaser under an agreement for a period that begins before the effective date and end on or after the effective date.
3. Eligibility for deemed Input Tax under Regulation 47 of the GST Regulations 2014.
4. Claiming special refund of sales tax goods held on hand on 1 April 2015.
5. Whether a debit note is allowed to be issued in order to recover the GST amount during transitional?

It also includes amendment of the previously issued GST Frequently Asked Issues on :-
1. Claiming bad debt relief
2. Foreign Exchange
3. Motor cars used exclusively for business purposes as approved by the DG.
4. Gift rule.

The DG has confirmed that the following goods do not qualify for a special refund:
(a) goods which have been sold and subsequently repurchased (buy back) by the supplier or returned to the supplier before 1st April 2015;
(b) petrol Ron 95 and diesel; AND
(c) The goods listed under the GST (Zero Rated Supply) Order 2014

Source : RMCD website

Monday, February 09, 2015

GST DG's DECISION NO. 1/2015

On 6 February 2015, the Royal Malaysian Customs Department (RMCD) has issued the decision on GST Frequently Asked Issues (or DG's Decision), FAI 1/2015. The GST issues related to the following:-
  1. Late date to issue invoice under the Sales Tax or Service Tax.
  2. Goods received free and give away free.
  3. Price display.
  4. Supply of SIM (Subscriber Identification Module) card prepaid or post paid. i) In Designation Area  ii) Free of charge  
  5. Approval of simplified tax invoice.
Source : RMCD website

Friday, January 16, 2015

GST : HANDBOOK ON LIST OF SUNDRY GOODS

On 15 January 2015, Royal Malaysian Customs Department (RMCD) has uploaded the handbook on the list of sundry goods on their website. The list consists of 13 categories of sundry goods. 

The handbook can download from RMCD website.

Source : RMCD website

Friday, January 02, 2015

GST FREQUENTLY ASKED ISSUES NO. 4/2014

Today, the Royal Malaysian Customs Department (RMCD) has issued the decision on GST Frequently Asked Issues, FAI 4/2014. The GST issues related to the following:-
  1. Supply by Societies and Similar Organisations (Including Charitable Entities)
  2. Issue tax invoice before effective date
  3. Issue tax invoice for exempt supply
  4. Registration of receiver or liquidator
  5. Supply of goods under lease agreement from Designation Area (DA) to Principal Customs Area (PCA)
  6. Individual supply commercial property
  7. Land Development Agreement between a land owner and a developer
  8. Supply of land or property during transitional period
Source : RMCD website

GST FREQUENTLY ASKED ISSUES NO. 3/2014

On 24 December 2014, the RMCD has issued the RMCD’s decision on GST Frequently Asked Issues No. 3/2014 comprising the following: 

a) Type of newspapers that fall under the GST (Zero Rate Supply) Order 2014
b) GST treatment on supply made by the healthcare professional
c) Further explanation to item no. 8 Frequently Asked Issues 1/2014 for GST treatment on Office holders/ directors’ fees

Source : RMCD website.

Tuesday, October 14, 2014

Recommended GST Tax Codes

GST Tax Code for Purchase

   TX-CG    6%           Purchase of capital goods or assets

The most common GST tax codes used for purchase are :


Tax code
Description
Example
TX
Input tax code used for business purchases from GST registered suppliers
Purchase of goods….
IM
Input Tax code used for business purchases from GST registered suppliers
Purchase imported goods
BL
Blocked input tax
Entertainment for potential customer & supplier, Medical & PA insurance for staff, Club subscription fee, Medical expenses, Expenses incurred for passenger car…
NR
Purchase from non-registered supplier
Upkeep of premises paid to non-registered supplier
ZP
Zero-rated purchases from GST registered supplier
Newspaper
EP
Purchases exempt from GST
Bank interest, Bank charges, Toll charges, Medical fee, Fare for public transport...
OP
Purchase of goods out of scope of GST
Expenses incurred in oversea for business purpose, Quit rent and assessment, Penalty, Licence fee, Staff costs....
AJP
Any adjustment made to input tax
Customer fail to pay after 6 months